Report Abstract
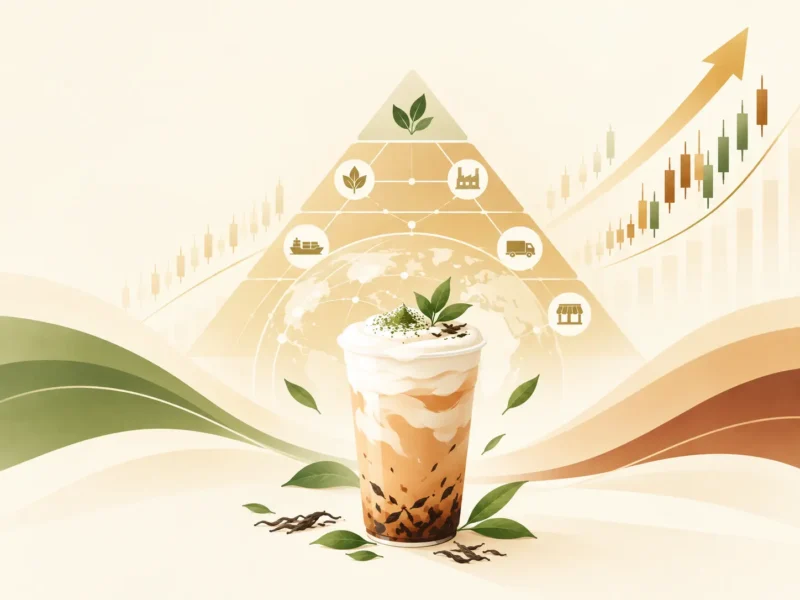
The white paper analyzes the 2025 development, core challenges, and future trends of China’s new tea drinks (new-style tea) industry from a capital-market perspective. Its central thesis is that the industry has entered a “year of capitalization”: within four months of 2025, Guming, Mixue Bingcheng, Chagee, and Auntea Jenny listed on the Hong Kong Stock Exchange (HKEX) and Nasdaq, joining the already-listed Nayuki and ChaPanda to form a “six-dragons” sector. The paper’s core judgment is that the market’s pricing anchor has systematically shifted away from store count and traffic growth toward supply-chain depth, profit quality, and counter-cyclical resilience. Two key figures anchor this argument: Mixue Bingcheng reached ~HK$150 billion (≈RMB 140 billion) market value on 2025 revenue of RMB 33.56 billion, while Nayuki — once valued above HK$30 billion — fell to roughly HK$1.8 billion, about one-hundredth of Mixue’s size. The report concludes that heavy-asset supply-chain investment has replaced traffic-driven expansion as the industry’s competitive moat.
1. Capital Market: IPO Wave Opens the “Year of Capitalization”
After nearly a decade of rapid growth, the industry reached a critical capital-market inflection in 2025. Within four months, Guming, Mixue Bingcheng, Chagee, and Auntea Jenny listed on HKEX and Nasdaq respectively, with combined financing scale and listing density reaching record highs — a phenomenon the industry has defined as the “first year of capitalization” (资本化元年). Together with the earlier listings of Nayuki and ChaPanda, the six leading brands (“six dragons”) now coexist on public markets, creating an unprecedented sector effect.
On listing venue choice: HKEX — favored for its understanding of consumer brands and improving liquidity — became the preferred venue for Mixue Bingcheng, Guming, and Auntea Jenny. Nasdaq welcomed Chagee, China’s first new tea drinks brand to list there, a choice consistent with its “Starbucks of the East” value narrative and its global-capital ambitions. The industry’s trajectory is striking: from Nayuki becoming the industry’s first unicorn at RMB 6 billion valuation in 2018, to Mixue Bingcheng now leading the sector at a RMB 100-billion-scale market capitalization.
The report attributes this IPO wave to a systematic shift in the industry’s underlying development logic. In the early phase, brands relied on venture-capital-driven expansion, with valuations anchored to store-growth and brand-mindshare narratives rather than profitability. By H2 2024, however, leading brands’ store networks had reached scale, supply-chain systems began to release cost-and-efficiency dividends, and profit models moved from heavy investment into profit release. The franchise model — asset-light with low fixed costs — demonstrated stronger resilience and cash-flow robustness during consumer-market volatility. At the same time, primary-market investment in the consumer sector turned cautious, making IPO both a clear exit path for early investors and a forcing mechanism for stronger corporate governance.
2. Valuation Divergence and the Systematic Reset of Valuation Logic
Within half a year of listing, the six listed companies showed drastic valuation divergence, revealing that valuation logic had shifted from a “traffic-scale” narrative to one centered on profit quality and capital efficiency:
- Mixue Bingcheng — 2025 revenue RMB 33.56 billion, net profit RMB 5.92 billion; market cap ≈ HK$150 billion (≈ RMB 140 billion), topping the sector.
- Guming — ≈ HK$60 billion market cap, second in the sector.
- Nayuki (the “first new tea drinks stock”) — market cap shrank from above HK$30 billion at IPO to ≈ HK$1.8 billion, roughly one-hundredth of Mixue’s.
- Chagee — listed on Nasdaq, but its valuation is likewise constrained by profitability.
The root cause is a fundamental shift in the market’s pricing yardstick. When industry growth slowed to single digits and saturation became visible, investors’ attention turned to unit economics: single-store daily sales, gross margin, store-closure rate, and the proportion of profitable franchisees. The market concluded that “store count does not equal profit.”
The core anchor of this revaluation is the supply-chain profit quality of the franchise model. More than 95% of Mixue Bingcheng’s revenue and more than 75% of Guming’s revenue come from selling raw materials and supply-chain services to franchisees. This model binds brand and tens of thousands of franchisees together: brand profit growth depends not on terminal price wars, but on cost optimization and category expansion driven by supply-chain efficiency. The market’s premium valuation essentially rewards brands that turned a “traffic business” into an “infrastructure business.” By contrast, Nayuki — a heavy-asset direct-operation model — bears high rent and labor costs that cannot be diluted through scale, trapping it in a “revenue growth without profit growth” bind. Chagee’s 2025 growth slowdown also showed that a high-premium path faces severe tests once price wars redefine the market.
3. Fund Deployment: From Store Expansion to Supply-Chain Infrastructure
In parallel with valuation divergence, fund deployment shifted structurally. Early financing went mainly to store expansion, brand marketing, and traffic acquisition; 2025 listing proceeds pointed squarely at supply-chain depth and headquarters-economy construction — a migration from “front-end store arms races” to “back-end heavy-asset infrastructure.” Mixue Bingcheng’s prospectus lists expanding central-factory capacity and upgrading smart warehousing/logistics as a key use of proceeds; Guming and Auntea Jenny both prioritize digital-operations middle-platform iteration and cold-chain distribution networks, plus R&D and quality-control centers.
This reflects a collective awakening to “supply-chain depth” as the core moat. With terminal products increasingly homogeneous and hit-product innovation windows compressed to weeks, the real cost and standardization leverage lies upstream (raw-material control) and midstream (fulfillment efficiency). Self-built central factories enable in-house production of core toppings and tea bases, locking gross-margin upside inside the brand. Cold-chain logistics capability (“two-day delivery” or “next-day delivery”) directly determines ingredient freshness and inventory turnover for tens of thousands of franchise stores. This technology-driven efficiency was stress-tested during the annual “Autumn Milk Tea” traffic peak, when a digital backbone smoothly handled nearly 50 million cups of orders in a single day.
No comments yet